Index Annuity
Unlock your financial potential with our tailored Index Annuity solutions for a secure and prosperous future.
What is an Index Annuity?
An Index Annuity is a type of annuity that offers returns linked to a specific stock market index, such as the S&P 500. Unlike traditional variable annuities, Index Annuities typically provide downside protection, meaning that even if the stock market performs poorly, the policyholder will not lose their principal investment. One of the main benefits of an Index Annuity is the potential for higher returns compared to fixed annuities, while still providing a level of security. Additionally, many Index Annuities come with various options for income, making them an attractive choice for individuals looking to supplement their retirement income.
The Rule of 0%: Never Take a Step Backward
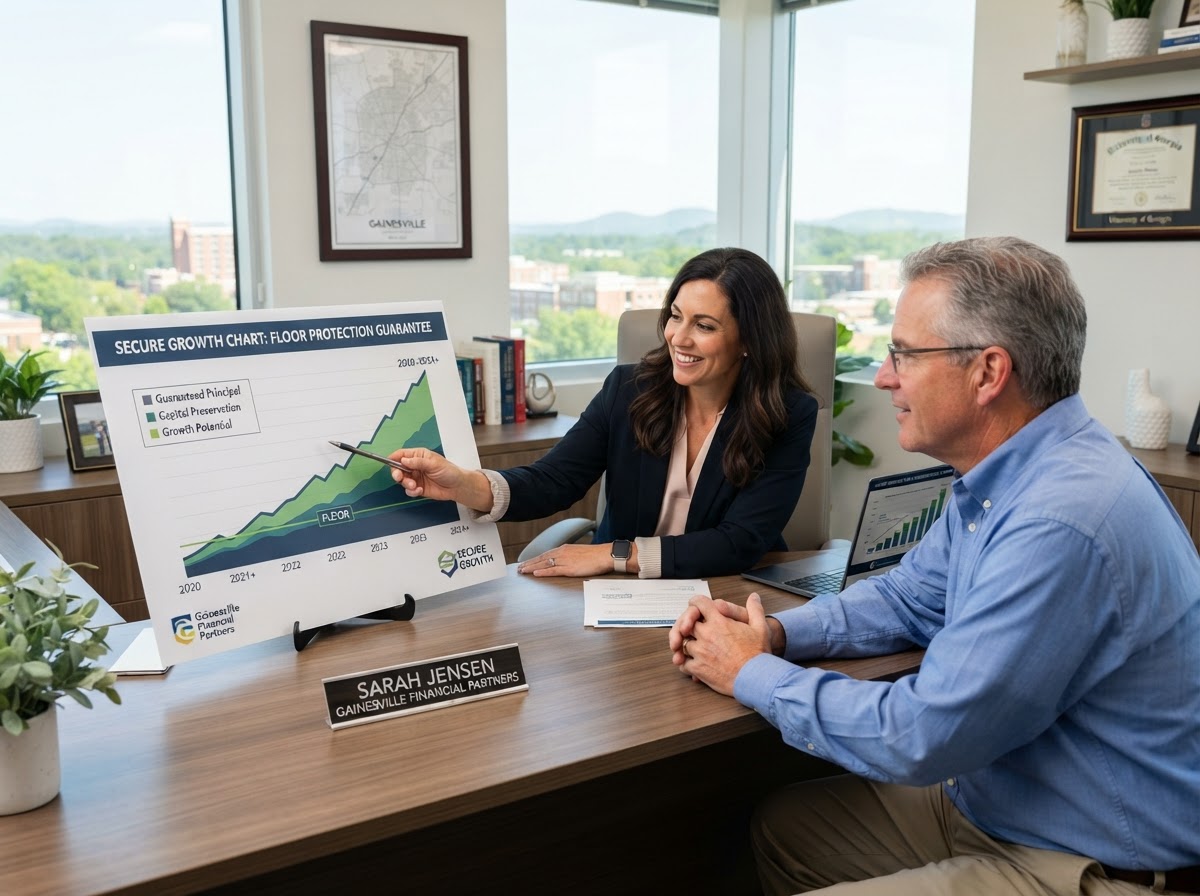
Zero is your hero. In a market crash like 2008 or 2020, while stock portfolios lost 30% to 50%, Index Annuity owners credited 0% — preserving every dollar of principal and prior gains intact.
Why Everyday Retirees Choose Index Annuities
A balanced bridge between risky equity markets and low-yielding traditional bank certificates.
0% Downside Floor Guarantee
When the market index declines, your credited interest is never less than zero. Your principal and previously locked-in interest are protected from market losses.
Market Index Growth Potential
Earn interest linked to positive performance of recognized market indices like the S&P 500 up to specified caps or participation rates.
Annual Reset & Lock-In
Any gains credited at the end of each index term are permanently locked in and become part of your guaranteed account value.
Guaranteed Lifetime Income
Convert your accumulated account value into a guaranteed paycheck you cannot outlive, creating a stable private pension for your retirement.
How an Index Annuity Grows Your Money
Plain, simple mechanics with no complicated Wall Street jargon.
You Select an Index Crediting Strategy
Your money tracks an external benchmark (such as the S&P 500) without ever actually being directly invested in the stock market.
Positive Years Add Interest
If the index rises over your contract crediting term, your account is credited with interest based on the cap, participation rate, or spread.
Down Years Trigger the 0% Floor
If the index drops 10%, 20%, or 30%, your account simply earns 0%. You don't lose a single dollar of your principal or past locked-in earnings.
Turn It Into Guaranteed Retirement Income
When you are ready to retire, you can turn your balance into predictable monthly income that lasts for as long as you live.
Index Annuity vs. Fixed vs. Variable
See how the three major annuity types stack up so you can make an informed choice.
| Feature | Fixed Index Annuity | Traditional Fixed | Variable Annuity |
|---|---|---|---|
| Downside Protection | 100% principal protection (0% floor) | 100% principal protection (fixed rate) | No floor; risk of losing principal |
| Growth Potential | Tied to positive index performance (with caps/rates) | Fixed low interest rate (often below inflation) | Direct equity subaccounts (highest risk/reward) |
| Tax Treatment | Tax-deferred until withdrawal | Tax-deferred until withdrawal | Tax-deferred until withdrawal |
| Annual Reset | Gains lock in annually; never surrendered to market drops | N/A (simple stated interest rate) | No reset; values fluctuate continuously |
| Lifetime Income Options | Optional guaranteed lifetime withdrawal benefits (GLWB) | Standard annuitization payout options | Lifetime rider options (higher ongoing fees) |
How Mr. G Helps You Build a Safe Income Plan
Annuities can be confusing because the fine print differs from carrier to carrier. As an independent agent in Gainesville, Mr. G shops across dozens of A-rated life insurance and annuity carriers to find the highest cap rates, the strongest income guarantees, and the lowest fees for your family.
- Side-by-side comparison of top carrier caps, participation rates & riders
- Direct tax-free rollovers from old employer 401(k)s and traditional IRAs
- Clear, honest explanations of liquidity rules and surrender periods
Frequently Asked Questions About Index Annuities
Is an Index Annuity the same as investing in the stock market?
No. You are not buying shares of stock or mutual funds. An Index Annuity is an insurance contract with an insurance carrier. Your money is protected by the claims-paying ability of the carrier, and you participate in the index's gains without risking your principal in the market.
What is the 0% floor and how does it protect me?
The 0% floor is the defining safeguard of Fixed Index Annuities. In years when the market drops, your credited interest is 0% rather than negative. Your principal and prior gains remain untouched and safe.
Can I roll over my existing 401(k) or IRA into an Index Annuity?
Yes. Many clients rollover all or part of an old 401(k), 403(b), or Traditional IRA into an Index Annuity on a direct, tax-free rollover basis to safeguard accumulated retirement funds against late-career market corrections.
How does Mr. G help you select the right annuity?
Not all annuities are created equal. Mr. G reviews surrender charges, cap rates, participation rates, and income rider fees across multiple top-rated carriers to match your precise timeline, liquidity needs, and retirement age.
Important Insurance & Annuity Disclosure: Fixed Index Annuities are insurance contracts issued by licensed insurance companies and are not insured by the FDIC, NCUA, or any federal government agency. Guarantees, including interest crediting and lifetime income payments, are backed exclusively by the financial strength and claims-paying ability of the issuing insurance company. Index annuities do not directly purchase shares of stock or equity funds. Surrender charges, market value adjustments (MVA), and IRS early withdrawal penalties may apply if funds are withdrawn prior to designated contract periods or before age 59½. G&A Financial Services does not offer legal, tax, or investment advice. Consult your licensed tax advisor or CPA regarding your individual circumstances.